55.4 vs 47.8: growth without headcount
Services output is at its fastest pace since February while services employment contracts, and acquirers are paying up for specialization: a $350 million healthcare IT bench, a $3 billion recruiting platform, a $3.2 billion HR platform. The Fed just made the permanent seat more expensive. Where the demand is landing, and what it means for how you build your workforce.
 Tony Buffum
Get this in your inbox every week. Join 26,000+ subscribers.
First, an invite to learn from your peers. So far half of companies plan to increase their usage of flexible talent, yet only a third have a formal policy.
| Take the survey to see early results » |
Here's what stands out this week:
- The Fed raised rates another 25 basis points. The move on Wednesday was very much in line with market expectations, as inflation concerns re-emerge. Higher borrowing costs should put additional pressure on hiring and investment, even as the labor market has remained relatively resilient.[1]
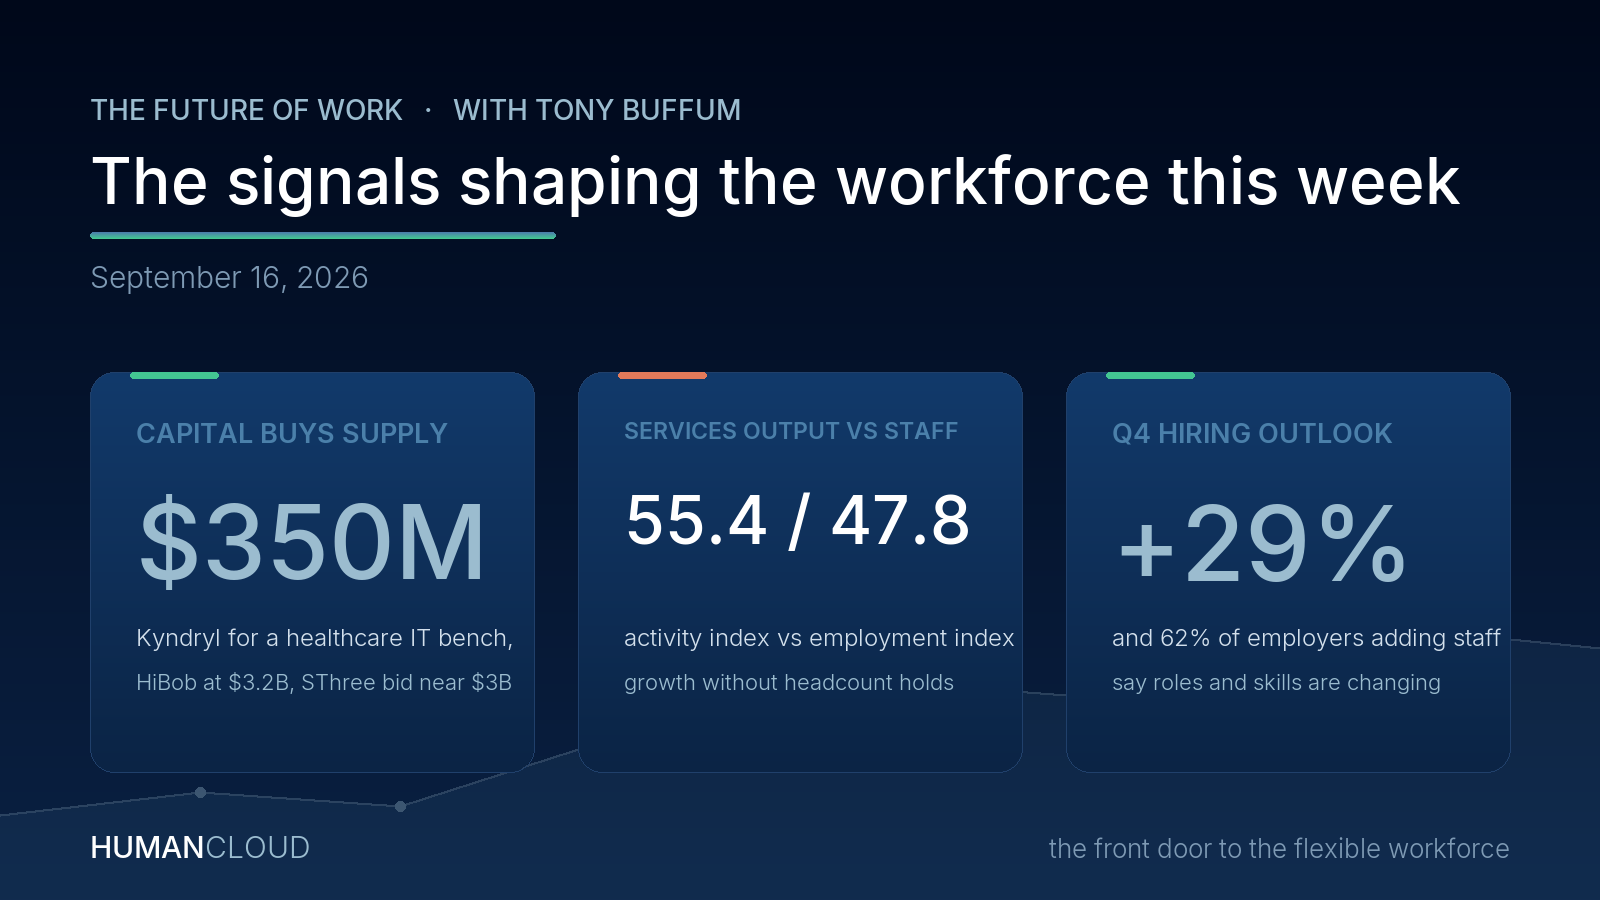
- Capital is buying the supply side. Circle8 made an all-cash approach for SThree that would create a recruiter with nearly $3 billion in gross revenue, and SThree's board rejected it as undervaluing the business.[2][3] Kyndryl paid up to $350 million for Healthcare IT Leaders.[4] Korn Ferry's AMS deal is already showing up as a 7% lift in fee revenue.[5] Salesforce led $166 million into HiBob at a $3.2 billion valuation.[6]
- Growth without headcount is holding. Services activity is at its fastest pace since February while services employment sits in contraction.[7] August added 162,000 jobs, and announced cuts rose 58% in the same month.[8][9] In the UK, permanent placements rose for the first time since 2022 while temp billings grew at the second-fastest pace in three years.[10]
- Hiring is turning to skills, not seats. ManpowerGroup's Q4 outlook climbed to +29%, and 62% of the employers adding staff say changing roles and skills are the reason.[11] Job openings are up 13% year over year while hires are up 2%, and nearly half of job seekers built AI skills on their own in the last six months against one in six who got them from an employer.[12]
|
Here's my interpretation of the data:
- The Fed move adds another layer to the talent story. Higher rates make growth and fixed headcount more expensive, which should keep pressure on employers to get more productivity from the workforce they already have and stay cautious about adding permanent roles.[1] That can create an opening for flexible talent, fractional expertise and project-based work, where companies can access capability without taking on as much long-term cost.
- There is an international dimension too. A higher-rate environment can strengthen the dollar, improving the relative economics of accessing talent in some global markets, although currency movements are never guaranteed. Put those forces together and the case for Talent Access - thinking about talent globally and flexibly - gets stronger, particularly for companies that still need specialized skills while keeping a close eye on cost.
- The gap between output and headcount is the flexible-workforce market. A 55.4 activity index against a 47.8 employment index is not a company that stopped needing people.[7] It is a company getting more done per employee and buying the rest. The UK says the same thing from the other side: permanent hiring barely moved while temp billings surged.[10] That gap is being filled with contractors, specialists, and project capacity, and it is the demand no headcount report counts.
- Acquirers are paying premiums for specialization they cannot build. A $350 million healthcare IT bench, a $3 billion tech recruiting platform, a $3.2 billion HR platform.[2][4][6] Incumbents are buying narrow, verified capability because generalist capacity is not what their clients are asking for. Two things follow for you. The way to fill your gap is specialized, verified capability, not another generalist agency. And when your supplier gets acquired, your rates, your account team, and your service model can all change before your contract does. This is the call we made last week. Capital just agreed with it, and the Fed made the alternative more expensive.
Here's how Human Cloud is helping:
Be in the room with your peers.
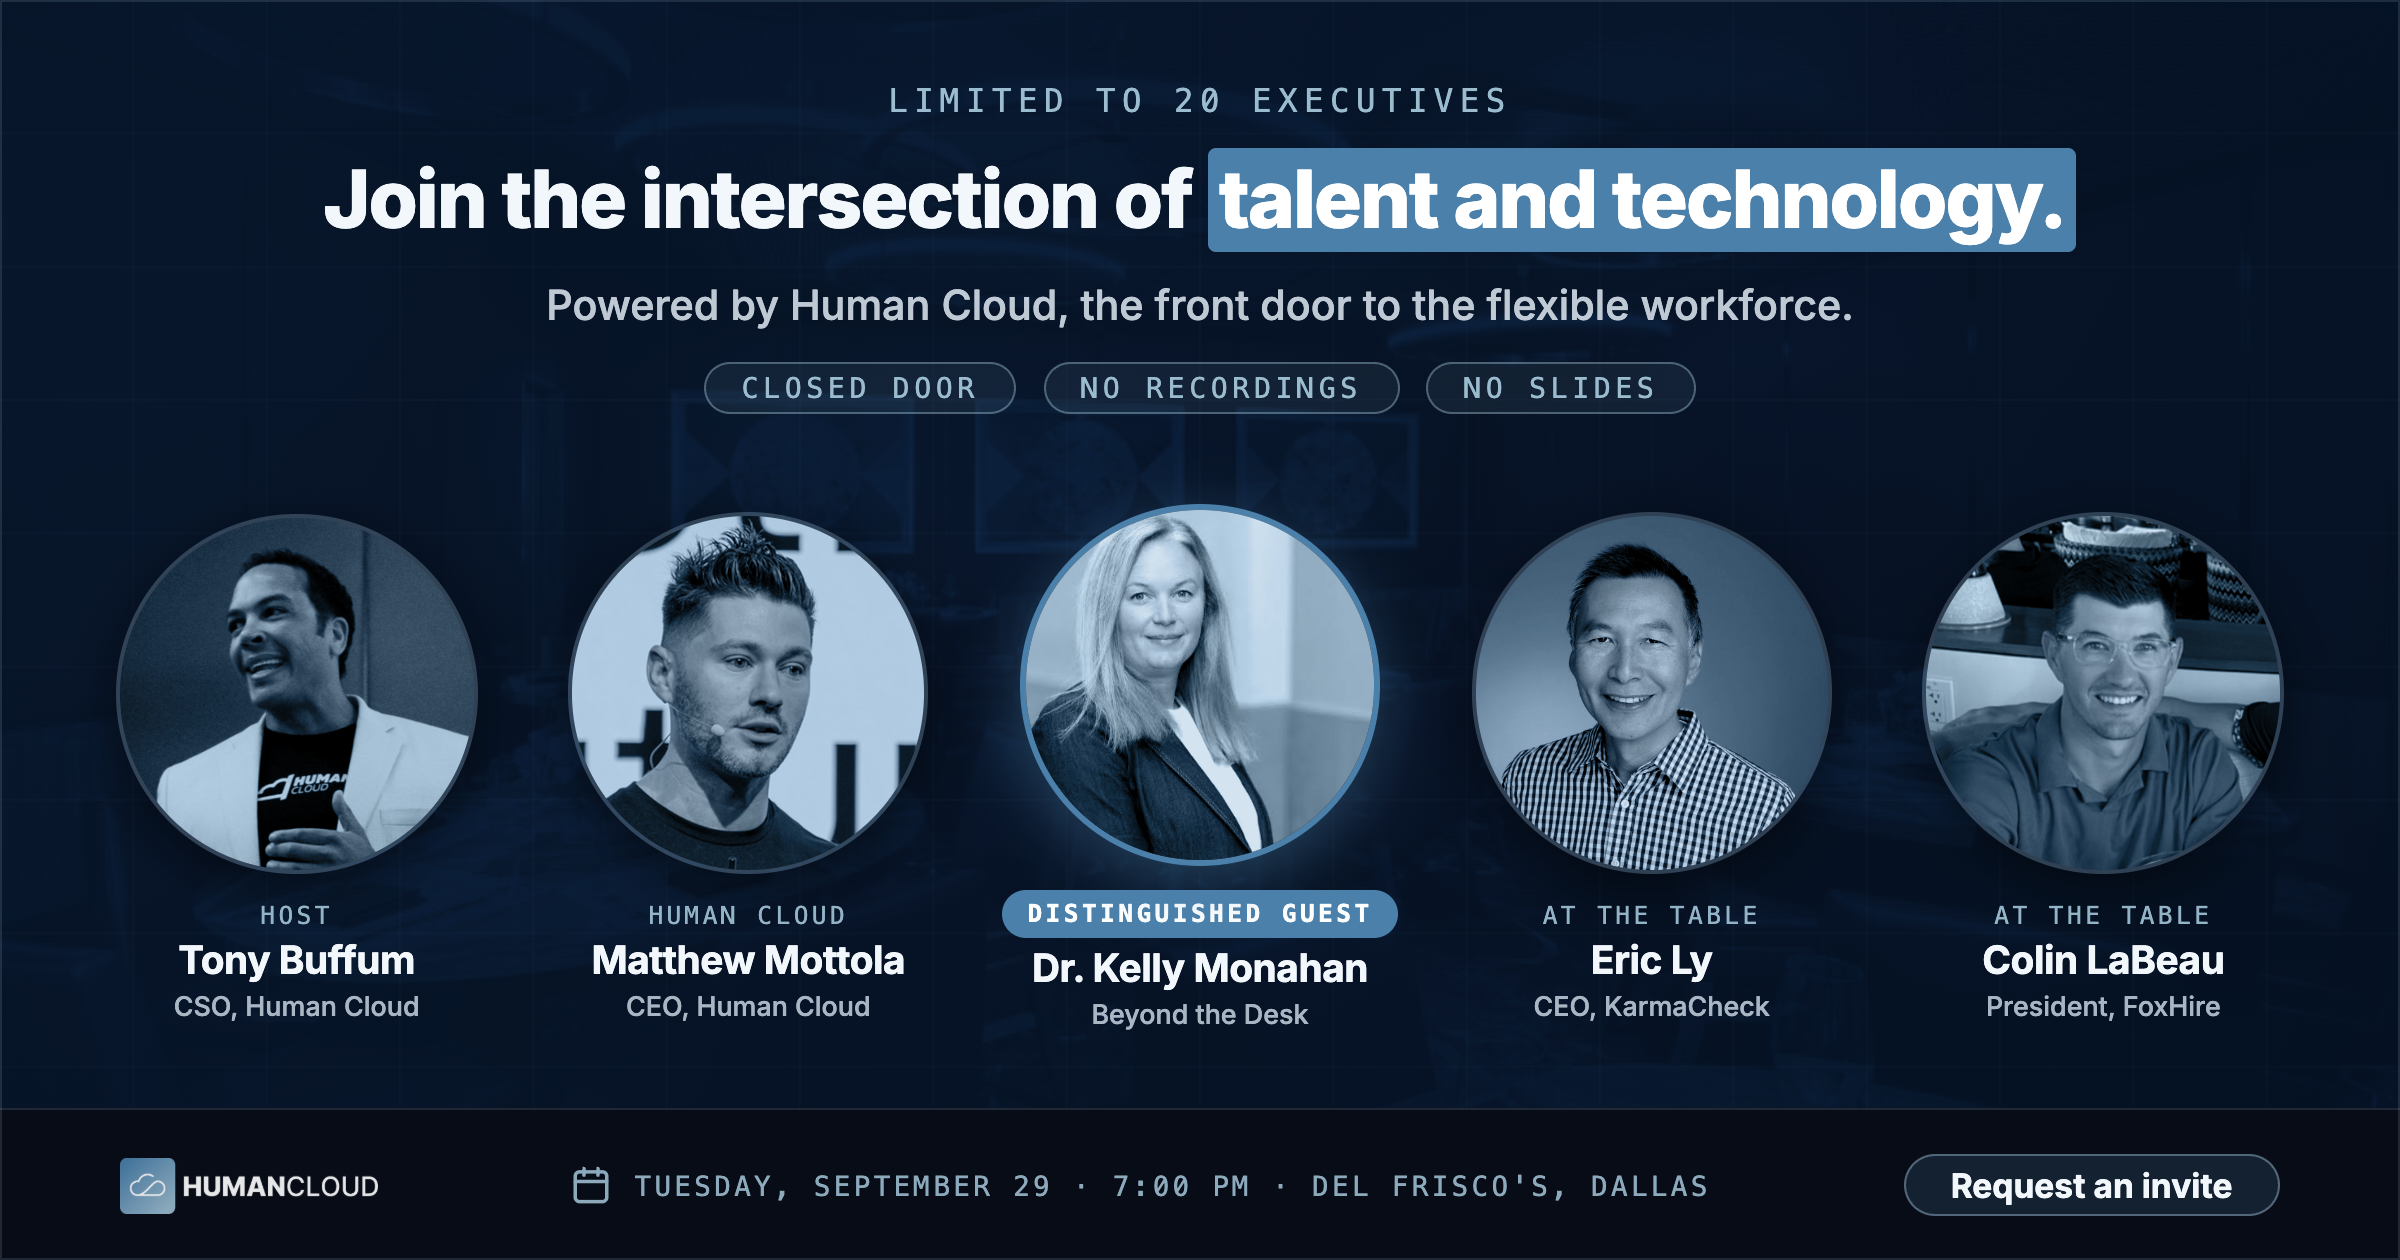
We are hosting twenty senior contingent workforce and talent leaders for dinner at Del Frisco's in Dallas on Tuesday, September 29, the last night of SIA's CWS Summit.
|
Twenty seats. Tuesday, September 29, Del Frisco's Double Eagle, Dallas.
| Request an invite → |
Can't be in Dallas? Book an Executive Briefing.
Schedule an Executive Briefing →
We'd love to see how we can help,
- Tony
|
Tony Buffum Co-Founder & Chief Strategy Officer at Human Cloud. 20+ years in global HR and talent transformation. Former CHRO at FLIR Systems, VP HR at Stanley Black & Decker, VP HR Client Strategy at Upwork. Grab time with me » |
|
PS: Heading to the PEI Operating Partners Forum in October? We are hosting a second executive dinner in New York on Tuesday, October 20, with Safeguard Global. Twenty seats, for private equity operating partners and portfolio talent leaders. Request an invite » |
Human Cloud Data
The back office is what companies are shopping for
Every 98 seconds, someone is looking at a solution profile on Human Cloud. Here is what they are searching to find them.
What the data shows
Business support searches rose 350% this month. Pharmacy rose 167%. Finance rose 150%. Aerospace and defense rose 100%. Software rose 67%. HR rose 60%. Healthcare and life sciences fell 33%, and strategy fell 40%.
That is the rate story showing up in our own data. When money gets more expensive, the first functions a company stops staffing are the ones that keep the lights on: finance, support, HR. It buys them instead. The categories rising this month are operating capability, not headline projects. The two falling, strategy and broad healthcare, are the ones a company can defer or has already bought. Content writing showed up as a search this month after none last month. In the last full week, 29 distinct categories were searched on the platform. Nobody is browsing an industry. They are buying a specific function off their plate.
| Business Support | +350% this month |
| Pharmacy | +167% this month |
| Finance | +150% this month |
| Aerospace and Defense | +100% this month |
| Technology SaaS | +67% this month |
| HR | +60% this month |
| Healthcare and Life Sciences | -33% this month |
| Strategy | -40% this month |
Percentages are this month vs last month.
|
Want to take action? Launch an RFP for your biggest challenges. Need a GCP-certified DevOps engineer? There was an RFP for that. A direct sourcing or FMS solution that plugs into your existing contingent ecosystem? There was an RFP for that. Launch an RFP → |
Sources
[1] Federal Reserve - FOMC statement, September 16, 2026
[2] SThree plc - Rejection of possible offer from Circle8 (RNS, September 11, 2026)
[3] Law360 - SThree rejects Circle8 offer to create nearly $3B recruiter
[4] Kyndryl - Completes acquisition of Healthcare IT Leaders for up to $350 million
[5] Korn Ferry - First quarter fiscal 2027 results; fee revenue up 7%
[6] HR Tech Feed - Salesforce leads $166 million investment in HiBob at $3.2 billion
[7] Institute for Supply Management - Services PMI at 55.4%, August 2026; employment index 47.8
[8] CNBC - U.S. payrolls rose 162,000 in August; unemployment rate at 4.1%
[9] Challenger, Gray & Christmas - August job cuts up 58% from July
[11] ManpowerGroup - Global hiring outlook strengthens for Q4 (+29%); 62% cite changing roles and skills
[12] iCIMS Insights - Workers are teaching themselves AI skills faster than employers train them
Get insights like this every week
Join 26,000+ leaders staying ahead of the flexible talent market.